Preparing for Economic Collapse: A Household Survival Guide
An economic collapse is not a single event you can dodge. It is a slow unwinding with bursts of speed: credit tightening, layoffs accelerating, prices climbing faster than wages, then a run on something and a weekend nobody forgets. By the time it is obvious, the cheap moves are gone.
The practical question is not whether you can predict it. It is what you can do this month that still helps if it never happens, and helps a great deal if it does.
What an Economic Collapse Actually Looks Like
Currency devaluation, bank failures, and supply chain breaks arrive together because they are symptoms of one thing: the system's promises stopped matching its capacity. Households experience it in a specific order. Essentials inflate first. Hours get cut. Credit tightens. Rent and mortgage stress arrives. Then non-essential services close and the informal economy takes over.
Knowing the sequence matters because it tells you what to fix in what order. The people who suffer most in a collapse are not those who lacked a bunker. They are those whose cash flow broke while their fixed obligations did not.
Start With Cash Flow, Not Gear
Before a single can of beans, do the unglamorous work. Know what your household spends monthly on essentials alone, and how many months you could cover that with liquid savings. Most families are shocked by the number. It is usually under two.
Then attack debt. High-interest consumer debt is the most dangerous position in an inflationary collapse, because the interest resets while your income does not. Second, build a cash reserve: enough to keep the lights on through a job loss, kept partly in physical cash at home because a bank holiday makes digital money temporarily inert.
Third, diversify income before you have to. A second skill, a side trade, a service you can sell locally. In a collapse, work becomes informal and local first. Someone who can repair, install, tutor, or fix things has an income that does not care what the currency is doing.
Food, Water, and the Resilience Stack
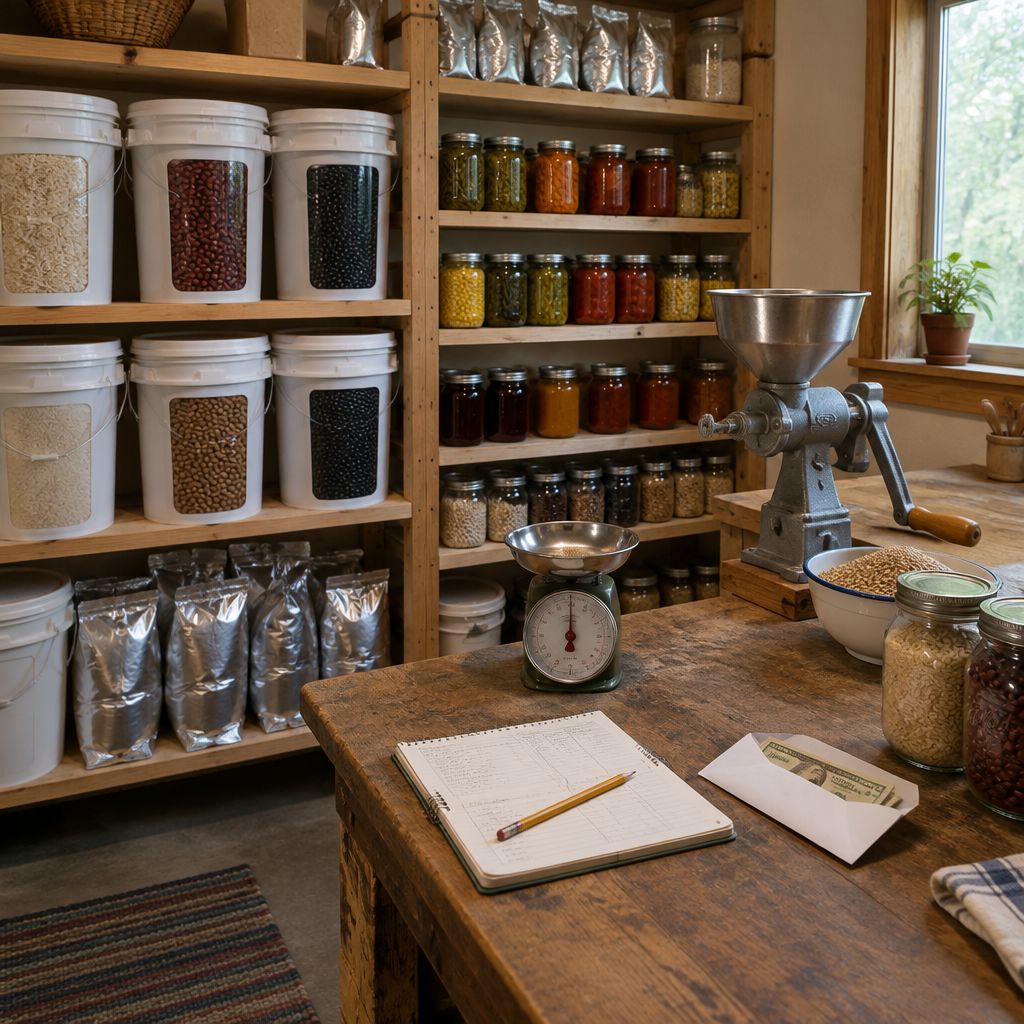
Food storage is where everyone starts, and the goal is not a year of rations. It is to stop being a price taker at the worst possible moment. Three months of food your family eats does more than a year of food nobody will touch. Buy in normal units, rotate, keep it dry and cool.
Water is where most collapse plans break. Municipal supply usually keeps working, but pumping, treatment, and billing can falter and boil-water notices are common. Store a gallon per person per day for two weeks, plus a way to make more: rain catchment and a filter that does not need electricity.
The Boring Items That Disappear First
If you want to know what to stock, look at what people panic-buy. Batteries, fuel, medicine, hygiene products, baby formula, pet food, coffee. These are not tactical. They are daily. In a currency crisis, imported goods and anything with a complex supply chain go first, which makes them strategically worth holding.
Fuel deserves specific attention. A collapse is a logistics crisis before anything else, and a household that can run a generator, a vehicle, and a cooking source for a few weeks has options that a household on empty does not. Store what you can legally and safely, rotate it, and treat fuel as insurance rather than supply.
Community Is Infrastructure
Social capital is the most underpriced asset in preparedness. Neighborhoods that know each other share information, watch property, pool tools, and cover each other's gaps. Neighborhoods that do not become targets for each other's anxiety. If you take one action this month that is not about stuff, make it about people: learn five neighbors' names, join the local group, offer help before you need it.
This is not sentiment. It is a survival function. Every serious disaster study finds that mutual aid networks outperform isolated households, often dramatically, in the first weeks.
What Not to Do
Two mistakes dominate. The first is spending a collapse budget on gear that solves the wrong problem: an expensive rifle in a crisis caused by a mortgage. The second is going all in on a single hedge, whether gold, crypto, ammo, or land. Concentration is a bet that you know which way this breaks. Diversification across cash flow, food, tools, skills, and community is a bet that you do not, which is the honest position.
Key Survival Takeaways
- Cash flow first, gear later. Fixed obligations meeting broken income is what actually ruins households.
- Kill high-interest debt early. In an inflationary collapse, the resetting interest rate is the enemy.
- Three months of food you eat beats a year of food you won't. Rotate it and store water to match.
- Stock the boring consumables. Batteries, fuel, medicine, and hygiene items vanish from shelves first.
- Build the neighborhood before the crisis. Mutual aid is a survival function, not a nicety.
Supplies Worth Having Before Prices Move
Everything below is dual-use: useful in a normal month, more useful in a bad one.
- Gravity Water Filter - treatment that does not need power or pressure
- Solar Generator and Deep-Cycle Battery - keeps a fridge and a radio alive
- Bulk Rice, Beans, and Mylar Storage - food security without a premium
- Indoor-Safe Backup Heater - winter outages are the classic collapse killer
- Fireproof Document Bag - deeds, IDs, and policies survive the transition
Disclosure: As an Amazon Associate, Survival Video Hacks earns from qualifying purchases made through the links on this page. We link to gear categories we judge relevant to the scenario, not the most expensive items.
Frequently Asked Questions
How do I know if a collapse is actually starting?
Watch the sequence rather than the headlines: essentials inflating faster than wages, credit tightening, layoffs spreading, and runs on a specific asset or bank. Two or three moving together is more meaningful than any one signal.
Is gold a good hedge?
Gold holds purchasing power over long periods, but it is illiquid in the first weeks of a crisis and useless for groceries. Treat it as a later-stage store of value, not a day-one solution.
How much cash should I keep at home?
Enough to cover several weeks of essentials during a bank holiday or payment outage, in small denominations, stored securely and separately from your documents.
What is the single best prep for economic collapse?
Reducing fixed obligations and building flexible income. Everything else is a supplement to that, and it is the one advantage you can build with certainty.
The Bottom Line
Economic collapse is survivable at the household level, but only if you work on it before it is a headline. Fix the cash flow, kill the expensive debt, store food you actually eat, keep water treatment that works without power, and invest the same energy in the people next door. For the trading side of a currency break, read our guide to bartering basics during a collapse, and for the logistics picture read fuel, food, power, and water planning. If a relocation is part of your plan, the bug-out bag builder quiz will tell you where you actually stand.
Get the next breakdown
New video articles, gear notes from the field and tool updates — one email a week.
No spam. Unsubscribe any time. We never sell subscriber data.

